If you are behind on your mortgage in Rhode Island, you still have real choices. You can ask for free foreclosure mediation, apply for relief from your servicer, sell the home before the lender does, or, in harder cases, negotiate a short sale or deed in lieu. The earlier you act, the more of these stay open. This guide walks through each option, what it costs you, and how to decide.
TL;DR
- Pre-foreclosure is the stretch after missed payments and before a foreclosure sale. Rhode Island gives eligible owner-occupants a right to mediation with the lender during it.
- Call your servicer and a HUD-approved housing counselor first. Counseling through RIHousing is free.
- If the home is worth more than you owe, selling before foreclosure usually protects your equity and credit better than waiting.
- If you owe more than the home is worth, a short sale, deed in lieu or bankruptcy may fit, and each has trade-offs worth understanding before you sign anything.
- A cash sale to a direct buyer is one fast route when time is short. It is not the only one.
Table of Contents
- What pre-foreclosure means in Rhode Island
- Step one: call your servicer and a housing counselor
- Option 1: Foreclosure mediation
- Option 2: Keep the home with servicer relief
- Option 3: Sell the home before foreclosure
- Option 4: Short sale
- Option 5: Deed in lieu of foreclosure
- Option 6: Bankruptcy
- How to choose: a short decision guide
- Our perspective
- When a cash sale fits
- FAQ
- Sources
What pre-foreclosure means in Rhode Island
Pre-foreclosure is the period after you miss payments but before the lender completes a foreclosure. It is not a single legal event with a start date. It is a window, and what happens inside it depends on your loan, your servicer and the notices you receive.
Two timing points matter. First, federal rules generally prevent a servicer from officially starting foreclosure until a loan is more than 120 days past due, with exceptions. That gives most borrowers time to submit a loss mitigation application. Second, Rhode Island requires lenders to follow notice and mediation steps under R.I. Gen. Laws § 34-27-9, and later to publish and mail notices of the foreclosure sale on set timelines.
The mediation rules apply to a first-lien mortgage on an owner-occupied, one- to four-unit property that is your primary residence. Under the state’s Department of Business Regulation rule, a foreclosure that skips the required mediation can be voidable. That is a strong protection, and it is a reason to read every letter you get.
Notices to watch for
- Notice of mediation conference. The lender must send it before moving ahead. Do not set it aside.
- Notices of foreclosure sale. These come later, once mediation is complete or does not apply, and they carry the dates that actually count.
- Servicer letters about loss mitigation. These explain the relief programs you can apply for. Respond in writing and keep copies.
Deadlines in these notices are the ones to calendar. If a letter is unclear, a housing counselor or an attorney can tell you what it means for your case.
Step one: call your servicer and a housing counselor
Before anything else, contact your mortgage servicer, explain your situation, and reach out to a HUD-approved housing counselor. Open every piece of mail from the lender, even the ones you dread. Missing a mediation notice can cost you a right you did not know you had.
In Rhode Island, RIHousing’s HelpCenter offers free, confidential foreclosure prevention counseling. A counselor can review your budget, explain the notices, and help you prepare a request to the servicer. Free matters here: be wary of anyone who charges an upfront fee to “save” your home.
When you call your servicer, write down the date, the name of the person and what was promised. Ask three things: how far behind you are in dollars, whether any relief application is pending, and whether a foreclosure referral has been made.
Option 1: Foreclosure mediation
Rhode Island homeowners who are delinquent have a right to a free mediation conference with their lender to try to reach a resolution and avoid foreclosure. The conference must be scheduled within 60 days after the coordinator receives the completed notice, the lender’s contact information and the initiating payment.
Bring what the lender will want: income documents, a monthly budget, a hardship explanation, and a clear idea of what you can pay. If you go in with a specific proposal, such as a modification or repayment plan, the conversation is more productive.
Two limits to know:
- If you fail an eligible workout agreement, mediation requirements do not apply to a foreclosure started within 12 months of that agreement. Treat any agreement as a serious commitment.
- If you cannot reach an agreement even though the lender made a good-faith effort, the lender may proceed after obtaining a certificate from the mediation coordinator. Mediation buys time and options. It does not stop a foreclosure forever.
Option 2: Keep the home with servicer relief
If you want to stay and your income can support a payment, ask your servicer or counselor about loan modifications, forbearance or repayment plans. They solve different problems:
| Option | Best when | What to check |
|---|---|---|
| Repayment plan | You had a short setback and income is back | Higher payments for a time to catch up |
| Forbearance | Income is temporarily reduced | How the paused amount gets repaid afterward |
| Loan modification | Your income dropped for good | New rate, term and whether the balance changes |
Get any offer in writing before you rely on it. Ask whether the foreclosure process pauses while your application is under review, and get that answer in writing too.
The honest test is simple: after the relief, can you pay the new amount every month for the foreseeable future? If the answer is no, a modification only delays the problem and may use up time you could have spent selling on better terms.
Option 3: Sell the home before foreclosure
You can sell during pre-foreclosure. The Consumer Financial Protection Bureau explains that selling is typically better for your finances and credit if the home is worth more than the mortgage. The sale pays off the loan and you keep what is left.
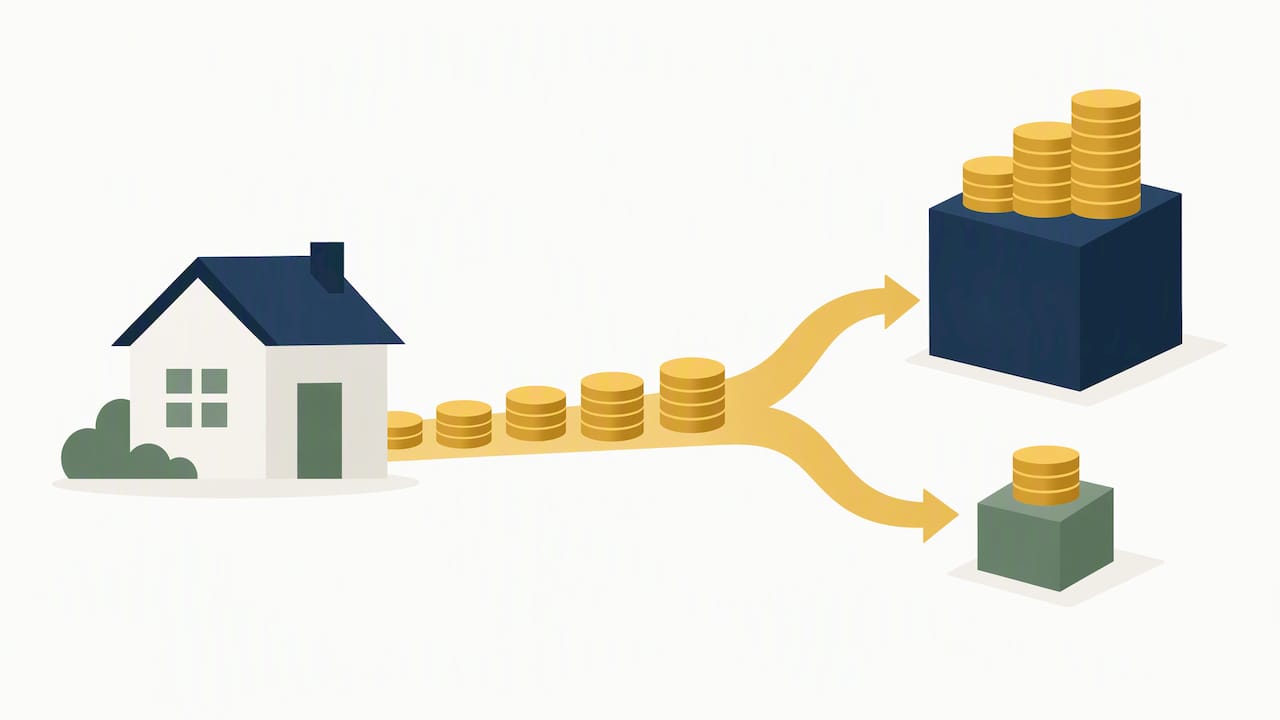
A quick example with made-up numbers: if your home would sell for $350,000 and you owe $290,000, you have equity to protect. A foreclosure sale usually brings less than a normal sale and adds costs, which come out of that equity. Selling first keeps more of it in your pocket.
You have three broad ways to sell:
- List with an agent. This can get the highest price when the home is in good shape and you have several months. It also means commissions, showings, repairs and a timeline you do not control.
- Sell as-is to a direct buyer. Faster and simpler, usually at a lower price than a fully repaired, listed home. We explain the price trade-off in our guide on whether to repair or sell as-is.
- Sell to an investor with cash. Closing can be quick and there are no agent fees, which suits a calendar driven by a sale date.
If a foreclosure auction is already scheduled, read our walkthrough on how to stop a foreclosure auction in Rhode Island, because the options narrow as the date gets closer.
Option 4: Short sale
A short sale means selling for less than you owe, with the lender’s approval. The CFPB notes that a short sale requires servicer approval to sell for less than the amount owed. That approval step is where short sales slow down.
Three questions to settle before you start:
- Will the lender accept the sale price as full satisfaction of the loan, or can it still pursue the gap? Get the answer in the approval letter.
- How long will approval take compared with your foreclosure calendar?
- Is there a second mortgage or lien that also needs to agree?
Because a buyer must wait on the lender, a short sale works best when you start well before a sale date. A housing counselor or a real estate attorney can help you read the approval terms.
Option 5: Deed in lieu of foreclosure
A deed in lieu is a voluntary agreement where you hand the property to the lender to settle the loan without a foreclosure case. Lenders often want proof of hardship and an updated valuation, and they may ask that the home be free of other liens. Whether you still owe a shortfall depends on what the lender agrees to, so insist on a written release of the remaining debt before you sign.
It can be less drawn out than foreclosure, but you give up the home and any equity. If the house is worth more than the loan, selling is usually the better path. A deed in lieu mostly makes sense when there is little or no equity and a short sale is not practical. Ask your servicer whether it offers one and what it requires.
Option 6: Bankruptcy
Filing for bankruptcy can pause collection actions, including a foreclosure, for a period, and certain chapters let you catch up on missed payments over time. It also has long-lasting consequences for credit and requires meeting eligibility rules. This is a decision for a bankruptcy attorney, not a quick fix. If you are weighing it, talk to a Rhode Island bankruptcy attorney early, and compare it with a sale: our page on selling before bankruptcy lays out when a sale can come first.
How to choose: a short decision guide
| Your situation | Options to look at first |
|---|---|
| Short setback, steady income again | Repayment plan, forbearance, mediation |
| Permanent income drop, home is affordable at a lower payment | Loan modification |
| Lots of equity, want out | Sell before foreclosure |
| Owe more than the home is worth | Short sale, deed in lieu, attorney consult |
| Sale date approaching, need speed | Sell as-is for cash, ask for mediation, attorney consult |
If a job loss started the problem, our guide to selling a house after a job loss in Rhode Island covers the practical steps.
Our perspective
Most of the homeowners who call us wait too long. They tell us they were embarrassed, or they hoped the next paycheck would fix it, or they did not open the letters. By the time they reach out, the calendar has made the decision for them.
Our advice is plain. Start with the free counseling and mediation, because they cost nothing and protect rights you may not know you have. Work out honestly whether you can afford to keep the home. If you cannot, sell while you still have choices, because a sale you control almost always beats one a lender forces.
We buy homes in Rhode Island for cash, as-is, with no agent fees or commissions and no repairs or cleaning. Our offers are based on the After Repaired Value of the home, and you pick the closing timeline that works for you. We are one option, and we would rather you know all of them. If our offer does not beat your other choices, we will tell you so.
— Dave
When a cash sale fits
A cash sale suits you when the home needs work you cannot fund, you have little time before a sale date, or you simply want a clean exit without showings. It fits less well if you have months to spare, the home is in excellent shape and you want top retail price.
If that sounds like your situation, you can request a no-obligation cash offer from Rhody Home Buyer and compare it with what a listing would net after commissions and repairs. Our page on how fast cash buyers work in Rhode Island shows the steps, and our guide on verifying proof of funds helps you check any buyer, including us.
Whatever you choose, run the numbers on what you would walk away with, not just the headline price. Subtract the mortgage payoff, any liens, closing costs and, if you list, commissions and repairs.
FAQ
Can I sell my house if it is in pre-foreclosure in Rhode Island?
Yes. You still own the home until a foreclosure sale is completed, so you can sell it. If the sale price covers the mortgage, the loan is paid off at closing and you keep the remainder. If it does not, you will need the lender’s approval for a short sale.
Do I have a right to mediation in Rhode Island?
If the loan is a first mortgage on your owner-occupied, one- to four-unit primary residence, Rhode Island’s mediation rules apply. The state’s DBR rule says a foreclosure that does not follow them can be voidable. A housing counselor can confirm whether your loan qualifies.
How long do I have before foreclosure starts?
Federal rules generally keep a servicer from starting foreclosure until you are more than 120 days behind, though exceptions exist. After that, Rhode Island’s notice and mediation steps apply, so the real timeline depends on your loan and servicer. Check your notices for exact dates.
Who can help me for free?
RIHousing’s HUD-approved HelpCenter provides free, confidential counseling for homeowners struggling with their mortgage. A counselor can also help you prepare for mediation and request relief from your servicer.
Do banks try to avoid foreclosure?
Often, yes, because foreclosure is costly and slow for lenders too. Servicers commonly have modification, forbearance and repayment programs, but you generally have to ask and submit documents. Starting early gives you more to work with.
Sources
- Rhode Island Foreclosure Process and Laws (Nolo)
- Homeowner Assistance Programs RI (RIHousing)
- Avoid foreclosure (Consumer Financial Protection Bureau)
- Mortgage Foreclosure Disclosure (Rhode Island Department of Business Regulation rule)