Yes, a transparent as-is cash sale to a reputable buyer can be a fast, legal way to raise funds and address mortgage obligations before you file. It often preserves more control and closes faster than a servicer-approved short sale. Your immediate next step: get a firm written offer and talk to a HUD-approved housing counselor before signing anything.
TL;DR:
- A direct cash sale can close in 7 to 21 days after signing if title is clear; short sales and deeds in lieu require servicer approval.
- Get a written offer stating the closing date and no repair requirements, verify proof of funds with a title agent, and contact a HUD approved counselor.
- Closing proceeds first cover the mortgage payoff, property taxes, valid liens, and fees; request a written net proceeds estimate before accepting an offer.
- Reject buyers demanding upfront fees or missed mortgage payments, and verify wiring instructions by phone with the title company before sending money.
- Eligible primary residence sellers may exclude up to $250,000 in gain, or $500,000 for couples filing jointly, if they meet IRS ownership and use tests.
Table of Contents
- Step-by-step action checklist to sell fast for cash
- How an as-is cash sale differs from a short sale or deed-in-lieu
- Money expectations: timeline, payoffs, and tax basics
- How to vet a fast cash buyer and avoid scams
- How Rhody Home Buyer approaches fast, as-is cash purchases
- Need to sell fast? Request a no-obligation cash offer
- FAQ
- Sources
Step-by-step action checklist to sell fast for cash
Selling quickly for cash works best when you move through a clear sequence rather than trying to do everything at once. Each step builds on the one before it, and skipping ahead usually costs you time later.
- Define your goal and gather your mortgage statement, payoff figure, title documents, and homeowners insurance paperwork.
- Request at least one firm written cash offer that spells out the closing date and confirms the sale is as-is, with no repairs expected.
- Contact a HUD-approved housing counselor and consider letting your mortgage servicer know you plan to sell.
- Work with a licensed title or settlement agent, confirm the buyer’s proof of funds, and sign a purchase agreement with clear terms before scheduling closing.
- Verify the exact payoff amount at closing and keep the written payoff and settlement statements as proof of your net proceeds.
Following this order keeps you from signing a contract before you know what you actually owe, which is one of the most common ways sellers get surprised at the closing table.
Pro Tip: Ask your buyer for a written closing timeline before you accept an offer, not after, so you can compare it against your own deadlines.
How an as-is cash sale differs from a short sale or deed-in-lieu
A direct cash sale is a private transaction between you and the buyer, funded by the buyer’s own money, which means you do not need your mortgage servicer’s approval to sell. A short sale or deed-in-lieu works differently: both require your servicer to review and approve the transaction, a process that can add weeks or months to your timeline, according to HUD’s loss mitigation training materials.
- A cash sale lets you set your own closing date once you have a qualified buyer.
- A short sale depends on your lender’s internal review, which you cannot control or speed up.
- A deed-in-lieu transfers the property to the lender instead of selling it, and it still requires servicer sign-off.
If you have equity in your home, the Consumer Financial Protection Bureau notes that selling can be a better outcome than foreclosure, avoiding the substantial average costs homeowners face from foreclosure. A direct sale that covers your payoff in full avoids that cost entirely and keeps the decision in your hands instead of your lender’s.
Money expectations: timeline, payoffs, and tax basics
A cash sale with no financing contingency often closes in 7 to 21 days once you have signed documents and a clean title. You can shorten that window by having your payoff statement and title paperwork ready before you accept an offer, which lets the title company start the payoff request immediately.
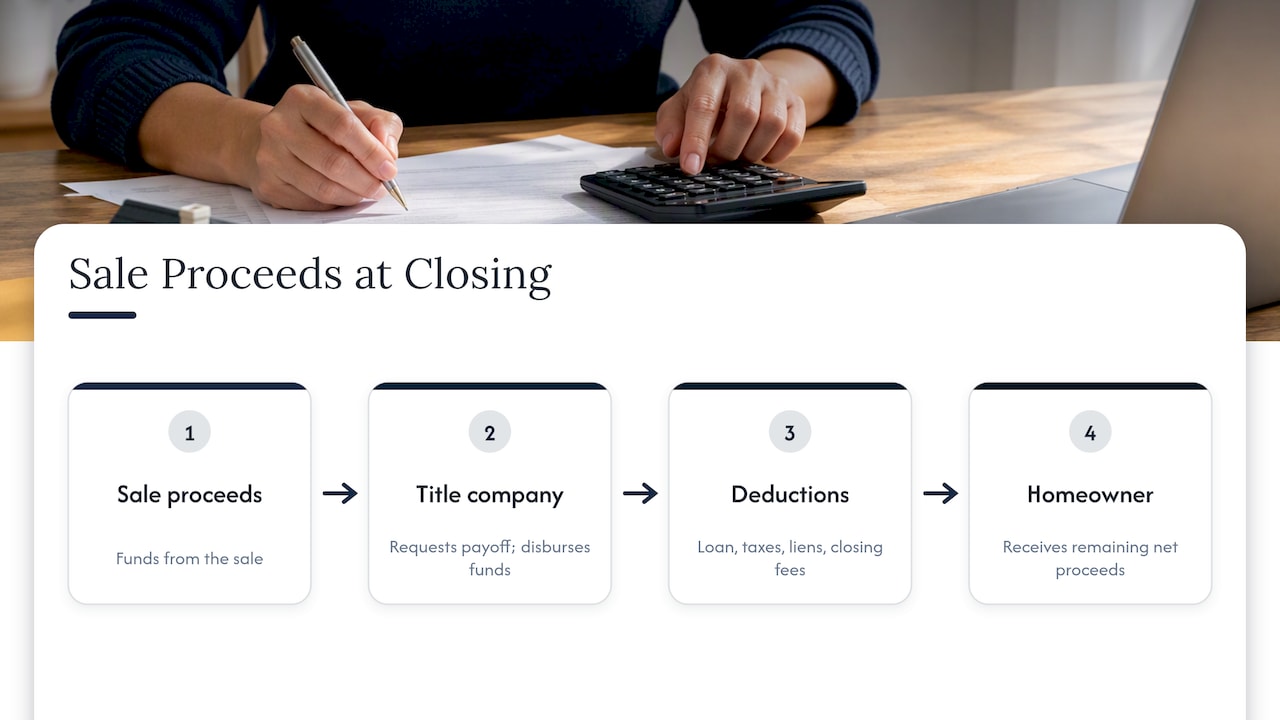
At closing, a licensed title company contacts your mortgage servicer for the exact payoff figure and disburses funds from the sale, settling the loan and any valid liens before you receive your share. Common deductions from your proceeds include the mortgage balance, unpaid property taxes, outstanding liens, and standard closing fees. Ask your buyer for a written net-proceeds estimate before you sign anything, so you know roughly what you will walk away with.
Most homeowners selling a primary residence can exclude up to $250,000 of gain from taxable income ($500,000 if married filing jointly), provided they meet the ownership and use tests described in IRS Publication 523. This exclusion covers the gain on the sale, not the sale price itself, and a tax professional can confirm how it applies to your specific situation.
How to vet a fast cash buyer and avoid scams
Not every “we buy houses” offer is legitimate, and the pressure of a looming bankruptcy filing makes you a target for bad actors. The Consumer Financial Protection Bureau and Federal Trade Commission both publish warning signs worth knowing before you sign anything.
- Watch for buyers who ask for up-front fees before any sale is complete.
- Be wary of anyone pressuring you to stop making mortgage payments.
- Never wire money or send payment based on instructions received only by e-mail. Verify wiring details by phone directly with your title company.
- Avoid rent-to-buy or contract-for-deed arrangements that shift title risk back onto you as the seller.
Before signing with any buyer, insist on proof of funds, use a licensed title company for closing, and confirm the buyer’s track record and paperwork independently. A nearby home-buying service in Northwest Indiana outlines a similar urgent-action checklist worth comparing against any offer you receive. HUD-approved counselors and the CFPB also accept scam reports if something feels off.
Pro Tip: Never vacate the property before escrow confirms the funds have cleared, and always request the final payoff and settlement statements at closing.
How Rhody Home Buyer approaches fast, as-is cash purchases
We buy homes as-is, which means no repairs, no cleaning, and no waiting on contingencies before we can close. We base our offers on the value of the home, and we work with licensed title and settlement agents on every transaction to make sure mortgage payoffs and lien releases are handled correctly.
We aim to close on the timeline that works for the seller, whether that means two weeks or a longer window depending on your situation. We also encourage anyone weighing a fast sale to speak with a HUD-approved housing counselor and to keep copies of every payoff and settlement document for their own records.
— Dave
Need to sell fast? Request a no-obligation cash offer
If a fast, as-is sale sounds like the right move for your situation, we make the process simple. We buy houses in any condition, we charge no agent commissions, and we coordinate directly with title companies to confirm your mortgage payoff before closing.
- Request a free, no-obligation cash offer through our Rhode Island home-buying page.
- Expect a closing window of 7 to 21 days once your paperwork is ready.
- If you are still deciding, a HUD-approved housing counselor can walk through your options with you at no cost.
Reach out whenever you are ready to see what a straightforward cash offer looks like for your home.
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
FAQ
Can selling my house before bankruptcy pay off my mortgage?
Yes, a cash sale with enough equity to cover your payoff can settle your mortgage at closing, with remaining funds going to you. The CFPB notes that selling can be a practical alternative to foreclosure for homeowners with equity.
How fast can a cash sale close compared to a short sale?
A direct cash sale can often close in 7 to 21 days since it does not require lender approval, while a short sale depends on servicer review timelines that vary widely. HUD’s loss mitigation guidance confirms that short sales and deeds-in-lieu typically involve longer approval processes.
Will I owe taxes on the sale of my home?
Most sellers of a primary residence can exclude up to $250,000 of gain ($500,000 for married couples filing jointly) under IRS Publication 523, provided they meet the ownership and use tests. A tax professional can confirm how this applies to your specific sale.
How do I know if a cash home buyer is legitimate?
Legitimate buyers do not ask for up-front fees or pressure you to stop paying your mortgage, and they work through a licensed title company for closing. Verify any wiring instructions by phone directly with your title company before sending funds, per FTC guidance.
What does Rhody Home Buyer charge to buy my house?
We do not charge agent fees or commissions, and our offers are based on your home’s value with no published flat fee. You can request a specific, no-obligation offer through our landing page.
Sources
- Publication 523 (Selling Your Home) | Internal Revenue Service
- Way to spot scams — how someone asks you to pay | FTC